
Bitcoin Magazine
How MSCI Shifted from Objective Benchmark to Defacto Market Regulator
For decades, the mechanics of global equity indexing were treated as background administrative plumbing. Providers like Morgan Stanley Capital International (MSCI) designed benchmarks to reflect public market economic realities rather than shape them. Their descriptive mandate served as a transparent mirror tracking global capital flows, sector weightings, and free-float market capitalizations.
That architectural assumption has quietly fractured. The immense scale of passive index-tracking capital has since elevated benchmark administrators into de facto market regulators. When an index provider sets eligibility rules for inclusion in benchmarks like the MSCI Global Investable Market Indexes (GIMI), it transcends mere market valuation; it dictates a company’s access to institutional capital, influences borrowing costs, shapes shareholder registers, and guides liquidity profiles.
This transformation is starkly visible in MSCI’s conflict with public Bitcoin treasury companies. Following a failed push in late 2025 targeting digital-asset holding vehicles directly, MSCI initiated a sweeping consultation on August 3, 2026, to redefine and restrict index eligibility for “non-operating companies.” Though written in neutral financial language, the framework threatens to eject major corporate Bitcoin adopters—most notably Strategy (formerly MicroStrategy)—from global benchmarks.
This clash goes beyond a routine index weighting dispute, raising a deep structural question: What happens when a for-profit index provider secures the power to penalize corporate balance-sheet innovation and exercise private market governance without regulatory accountability?
From Direct Exclusion to Structural Filters
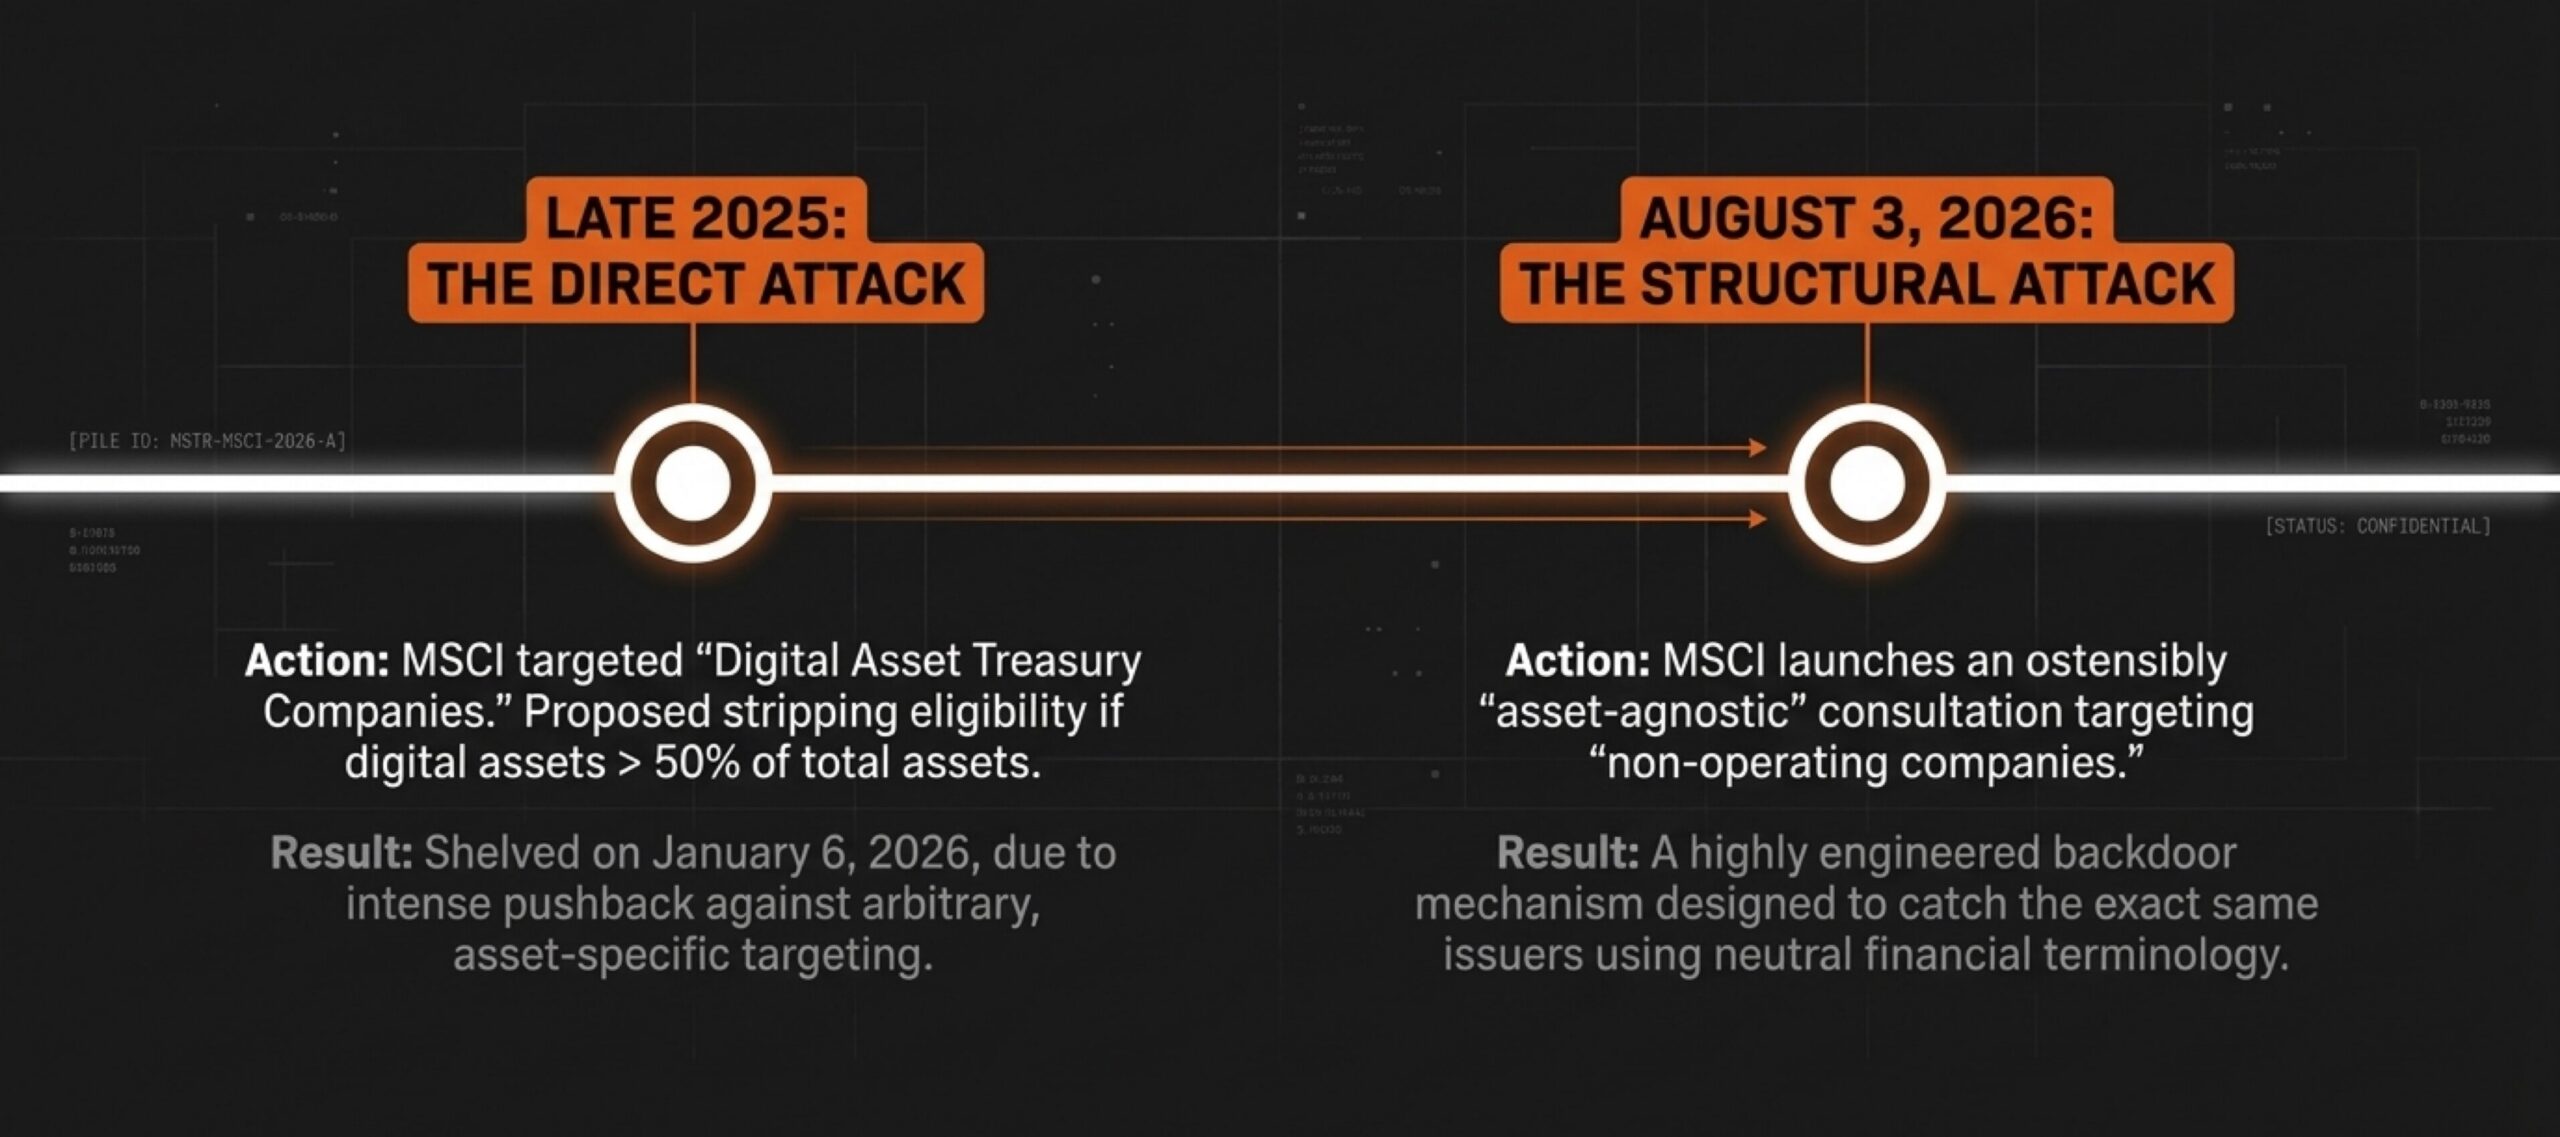
To trace this crisis, one must review MSCI’s regulatory actions over the past twelve months. In late 2025, MSCI opened a consultation focused on “Digital Asset Treasury Companies,” proposing to strip index eligibility from any issuer whose digital asset holdings reached or exceeded 50 percent of total assets. Participants immediately recognized this as a direct screen against companies pivoting their treasuries into Bitcoin.
Faced with heavy pushback from issuers and institutional investors criticizing the arbitrary targeting of a single asset class, MSCI shelved the direct approach on January 6, 2026. Rather than dropping the matter, the index provider developed a more sophisticated substitute.
On August 3, 2026, MSCI announced a broader, ostensibly asset-agnostic consultation regarding “non-operating companies” under the GIMI framework. Instead of naming Bitcoin outright, the new proposal introduces a two-step quantitative sieve to catch companies acting primarily as holding vehicles or investment funds rather than traditional operating businesses.
The methodology operates in two distinct stages:
- The Core Screen: MSCI applies a primary balance-sheet test to check if an issuer maintains substantial operating assets, clearing the hurdle if operating assets surpass 50 percent of total assets.
- The Exclusion Screen: For issuers failing the core screen, MSCI evaluates five non-industry-specific financial ratios: operating asset intensity, expense intensity, operating cash flow, fair value intensity, and capital dependence. Failing at least four out of five classifies the company as a non-operating entity, rendering it ineligible for index inclusion.
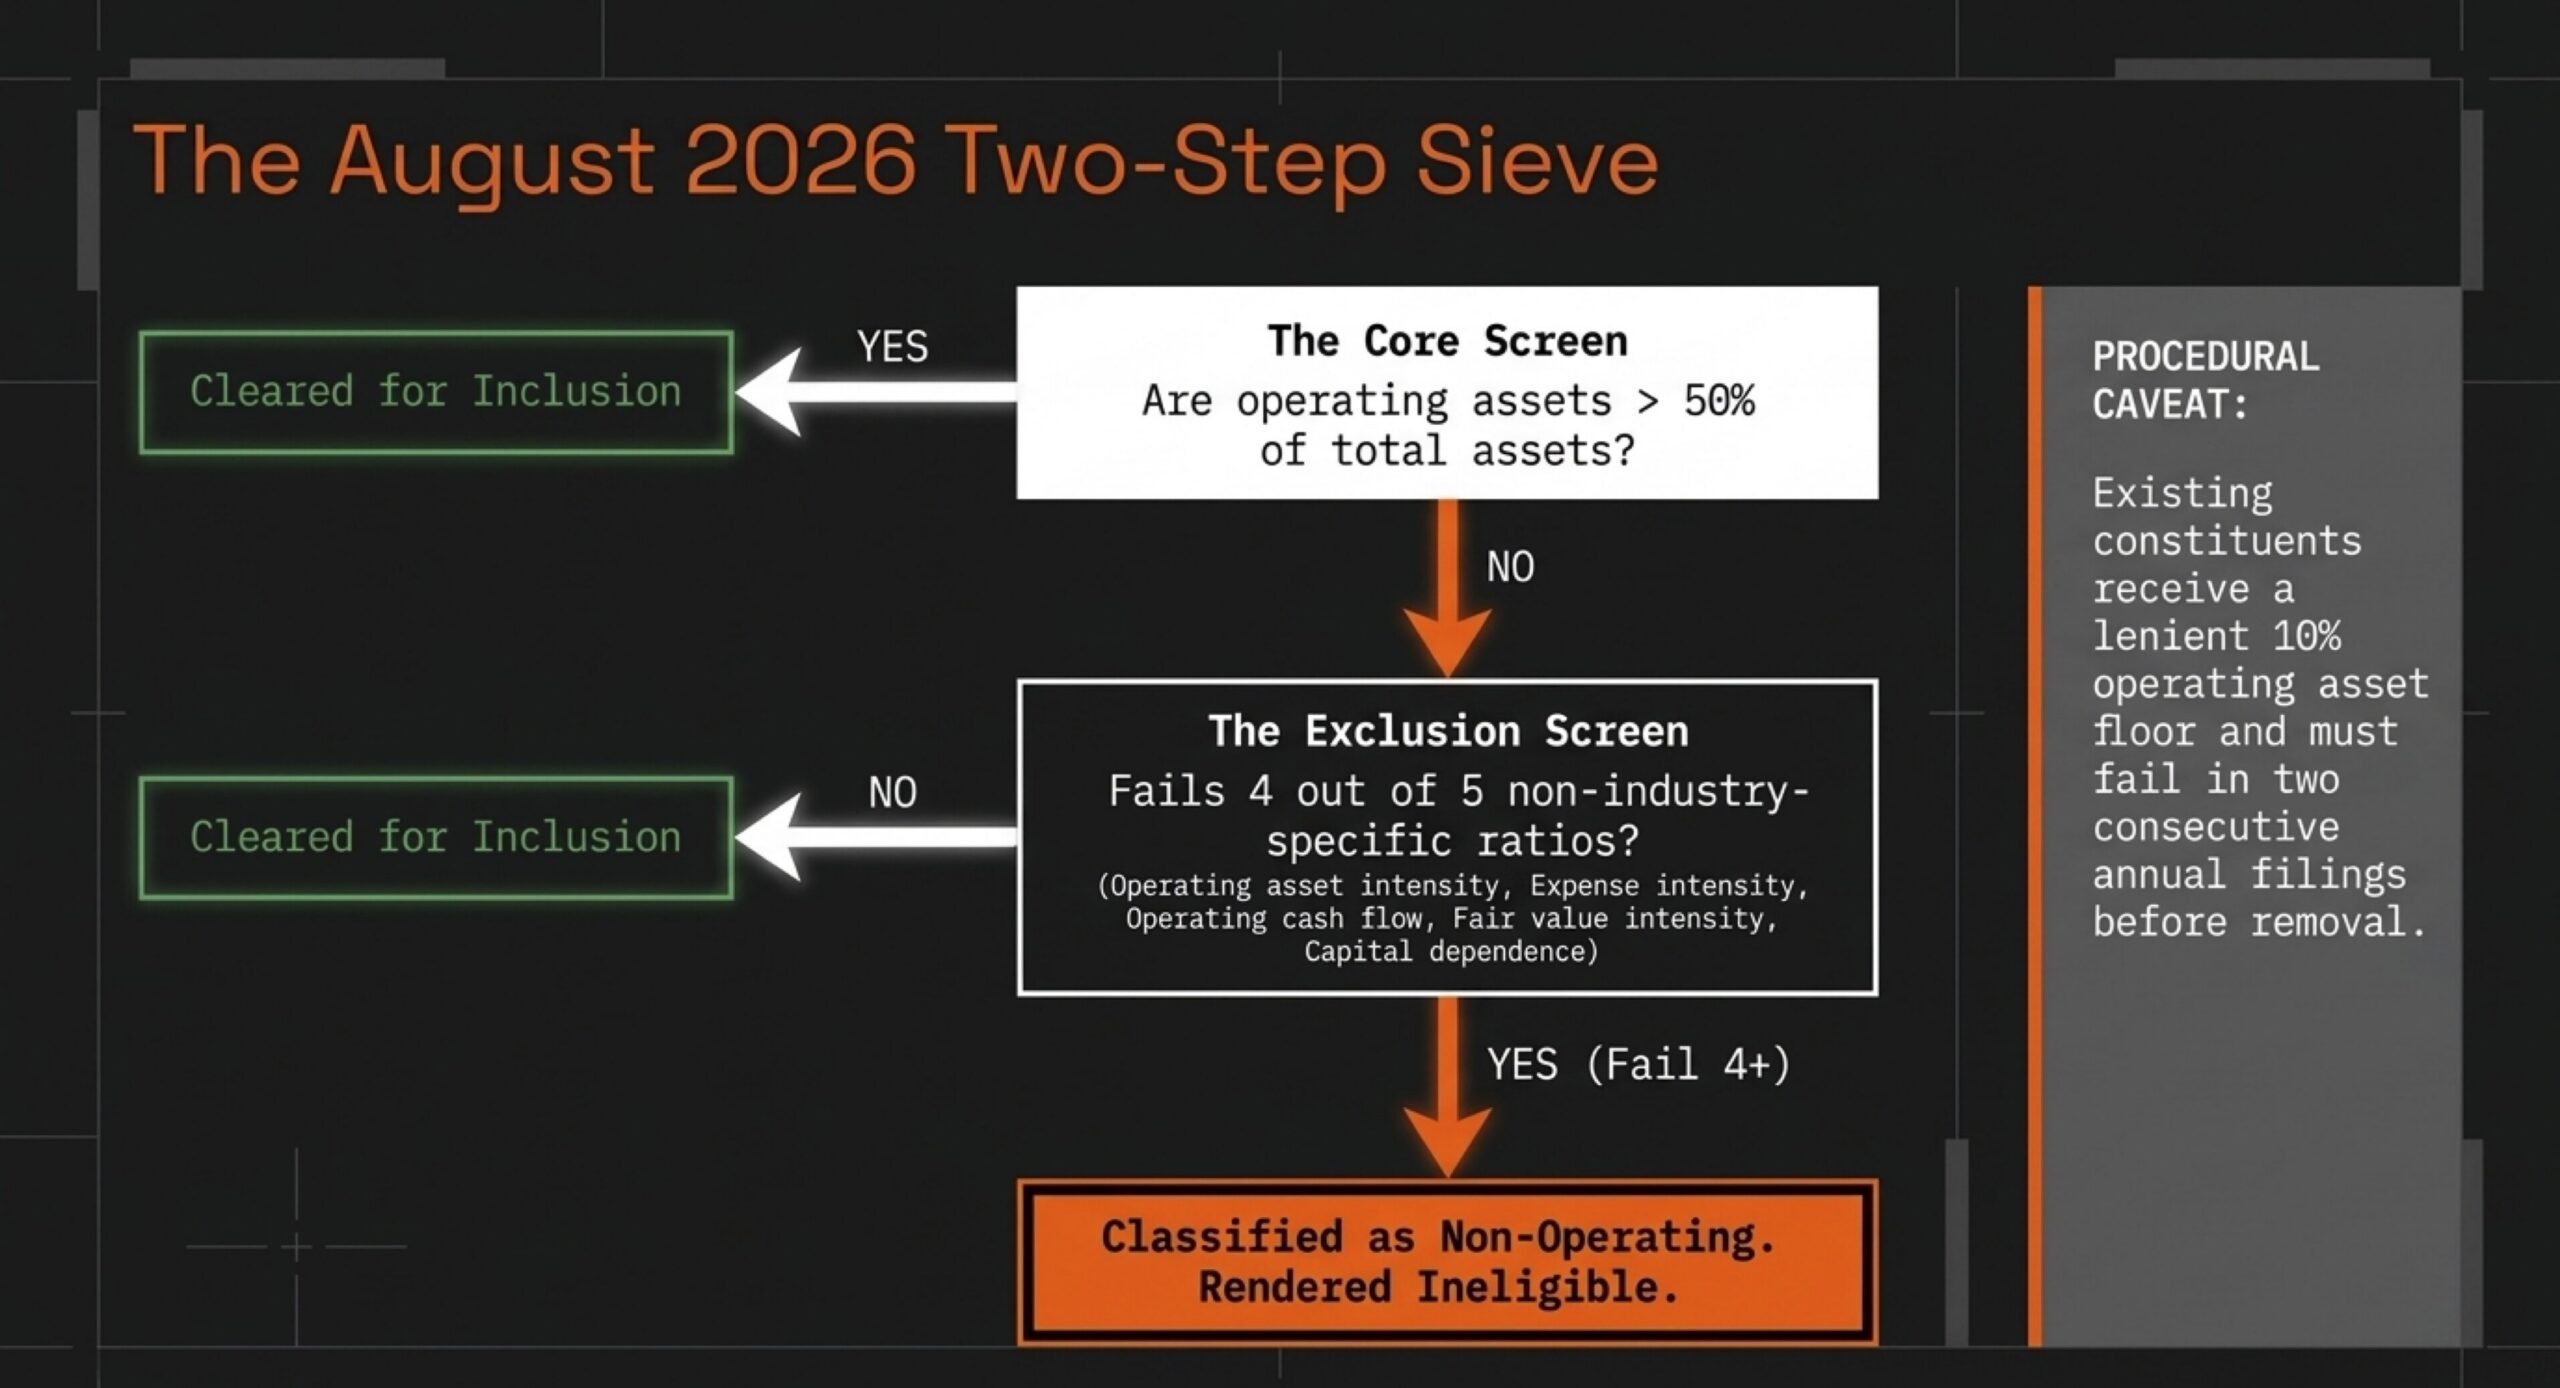
While existing constituents receive modest procedural protections—such as a more lenient 10 percent operating asset floor rather than 20 percent, and a requirement to fail the screen across two consecutive annual filings before removal—the structural intent remains clear. Simulations accompanying the August 2026 consultation showed that applying the screen to the MSCI ACWI IMI universe via mid-2026 data would immediately flag and delete major public Bitcoin treasuries like Strategy and Japan’s Metaplanet, alongside UK uranium holding vehicle Yellow Cake plc, while placing firms like SharpLink, Center Laboratories, and Lydia Holding on a public watchlist.
The Targets and the Quantitative Realities
The primary focal point of this methodology is Strategy. Following its multi-year pivot toward accumulating Bitcoin as its primary treasury reserve, Strategy holds over 845,050 bitcoin, making it the world’s largest corporate holder of the asset. In MSCI’s simulation data, Strategy—with a float-adjusted market capitalization over $23.9 billion among flagged entities—accounts for the vast majority of affected market value.
The financial stakes of index inclusion for a company of this scale are often misunderstood. Critics of corporate Bitcoin strategies frequently assume index exclusion triggers a terminal liquidity catastrophe. However, trading volume analysis paints a more nuanced picture. Industry estimates indicate passive funds tracking MSCI GIMI indices hold about 3.1 percent of Strategy’s basic shares outstanding, roughly 13 million shares. Measured against Strategy’s daily trading volume—where transactions regularly absorb hundreds of millions of dollars—that passive exposure represents less than a single average trading day.
Consequently, the true threat of MSCI’s proposal is not a mechanical liquidity shock, but a structural and narrative penalty. Index exclusion blocks access to specific institutional mandates, benchmark-restricted pension pools, and broad-market ETFs legally or contractually bound to replicate MSCI indices, penalizing companies for their balance-sheet structure rather than operational failure.
The Accounting and Legal Clash: GAAP versus Index Discretion
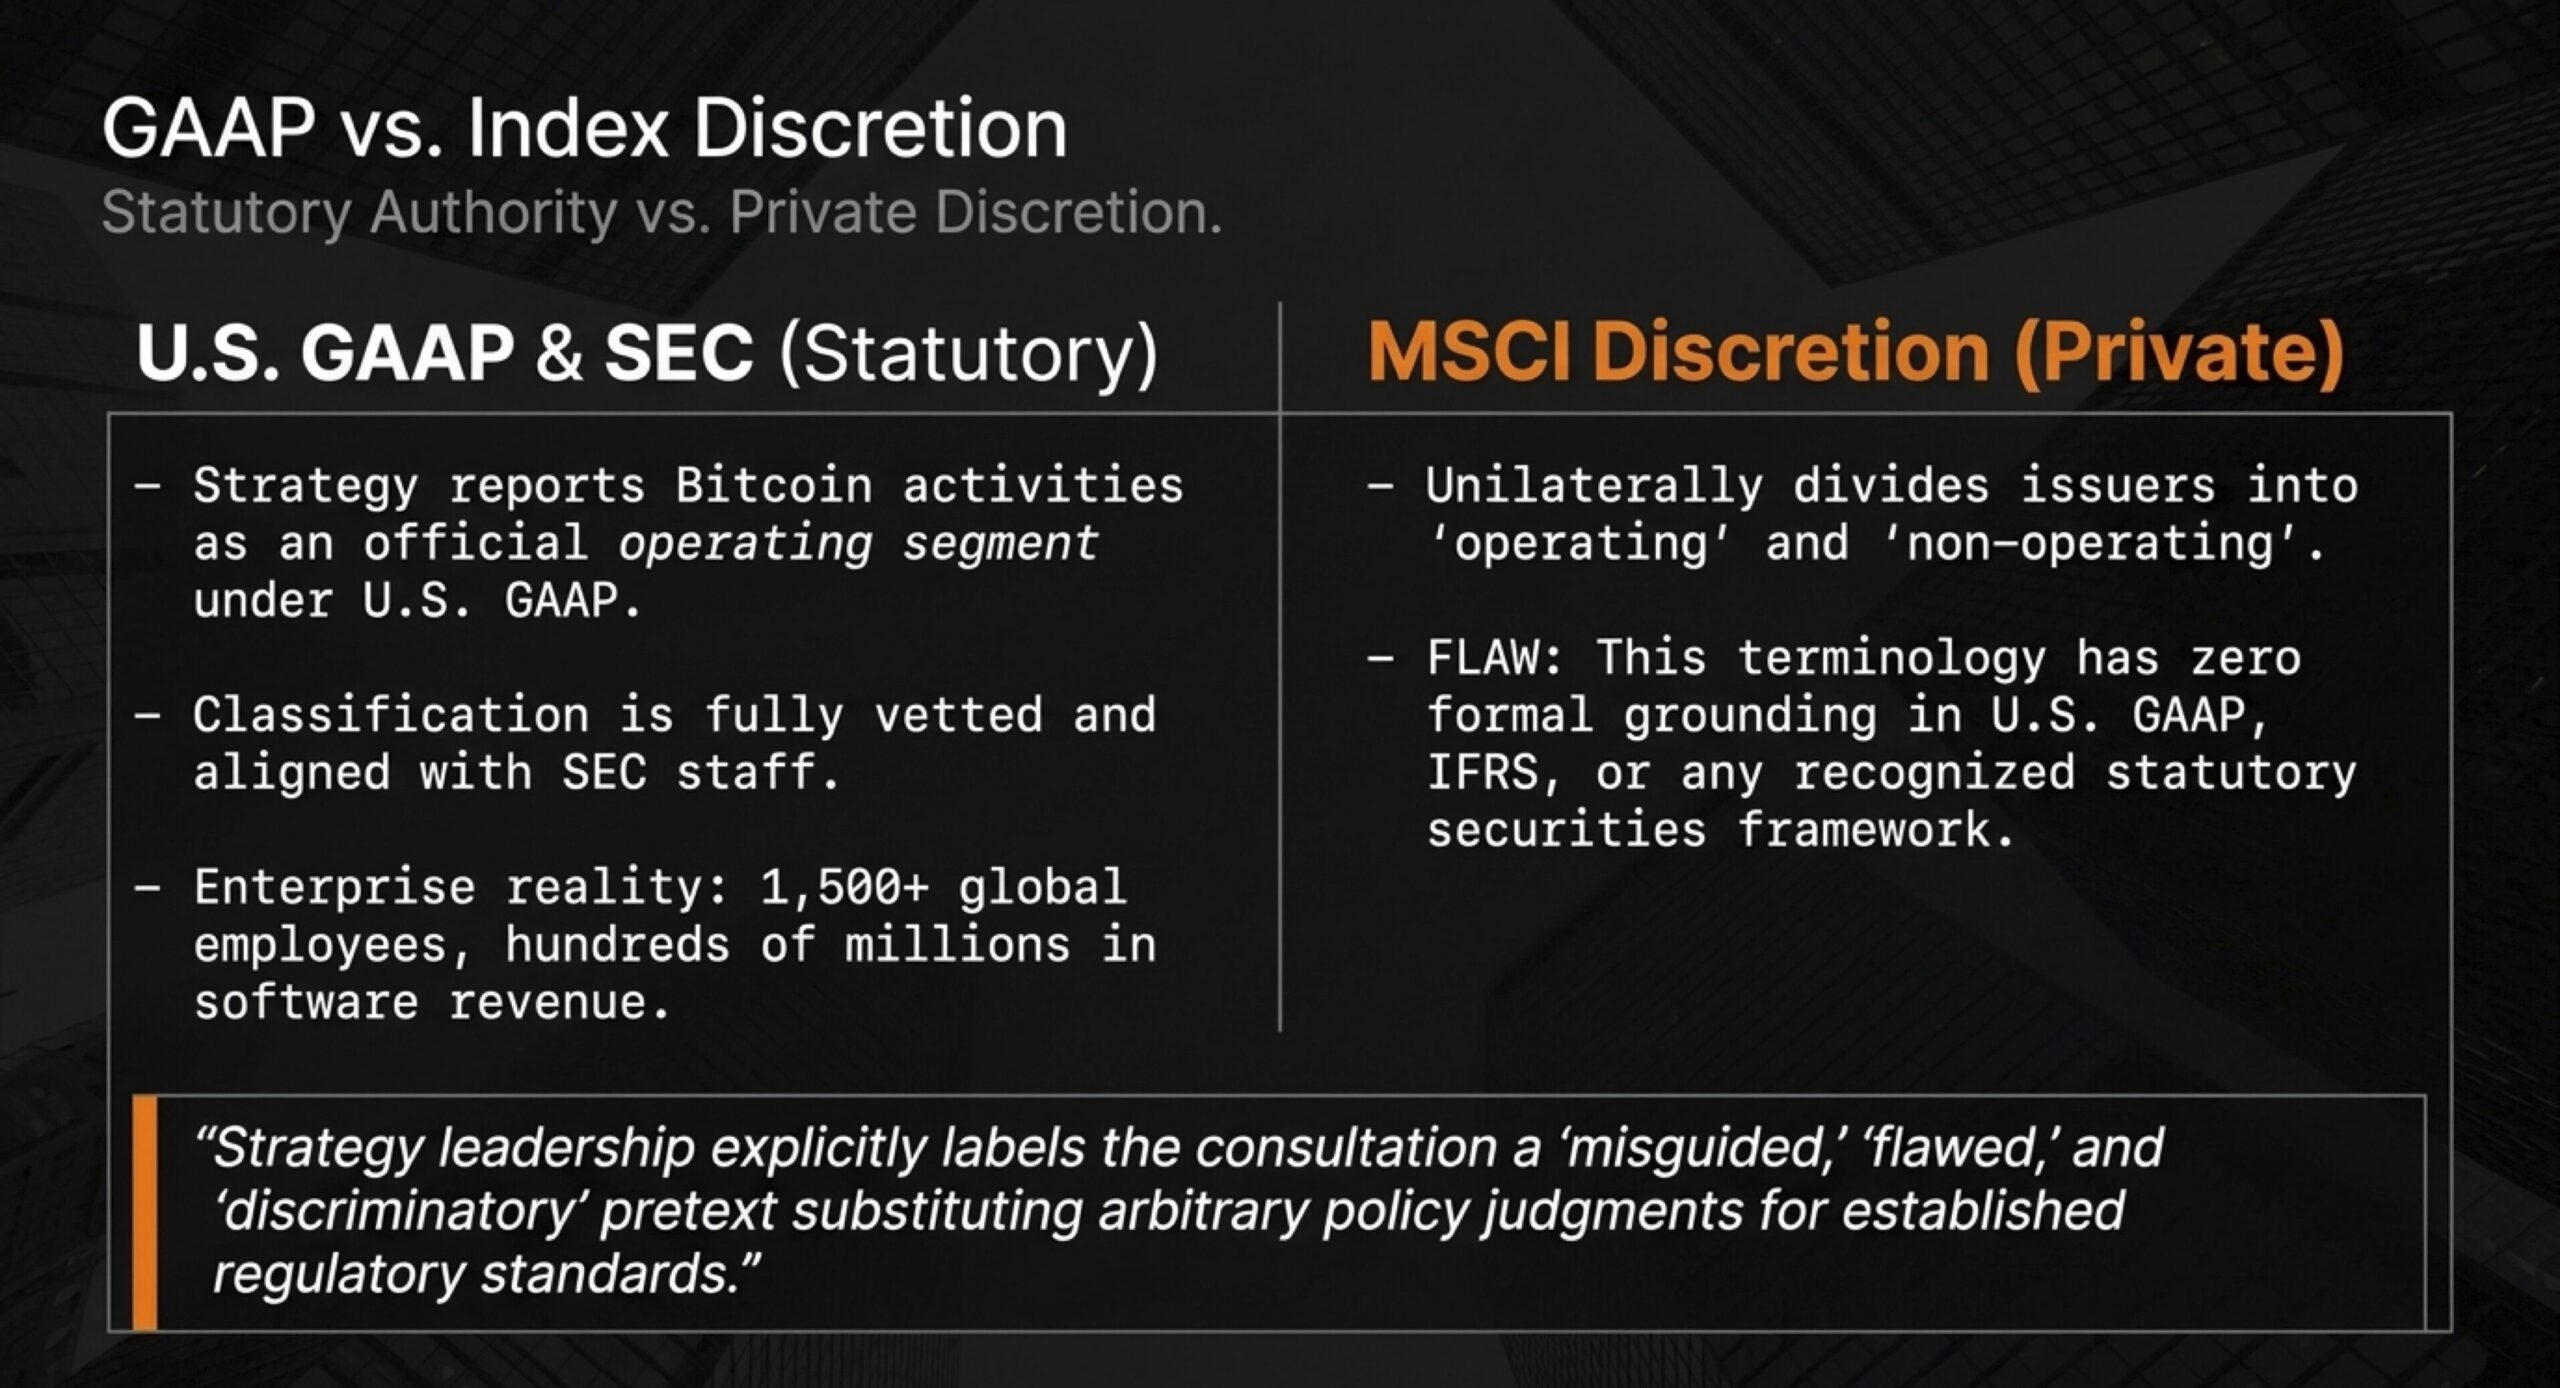
Strategy launched an aggressive counter-offensive in late August 2026, spearheaded by founder Michael Saylor and CEO Phong Le. In formal letters to MSCI and public filings, the company blasted the consultation as a “misguided,” “flawed,” and “discriminatory” pretext designed to achieve through backdoor ratio screens what MSCI failed to accomplish via its 2025 digital asset proposal.
Strategy’s legal and accounting arguments center on the definition of an operating business. The company pointed out that dividing issuers into “operating” and “non-operating” categories has no formal basis in U.S. Generally Accepted Accounting Principles (GAAP), International Financial Reporting Standards (IFRS), or any recognized statutory securities framework.
Furthermore, Strategy highlighted that it reports its Bitcoin activities as an official operating segment under U.S. GAAP, a classification established through extensive alignment with U.S. Securities and Exchange Commission (SEC) staff. By integrating Bitcoin treasury operations, capital markets issuance, and asset management as core segments of an enterprise employing over 1,500 people globally and generating hundreds of millions in software revenue, Strategy argues MSCI is substituting arbitrary policy judgments for established accounting standards.
In a sharp rhetorical turn, Strategy’s response leveraged MSCI’s own historical regulatory vulnerabilities. The company highlighted a 2022 SEC concept release examining whether information providers and index administrators hold enough market power to fall under the Investment Advisers Act. By forcing index providers to judge whether an asset class like Bitcoin belongs inside an operating business, MSCI risks undermining its foundational claim to absolute neutrality—the principle that index providers merely reflect market reality rather than passing moral or strategic judgments on balance sheets.
The Double Standard of Asset Concentration
Beyond technical accounting definitions, the institutional debate centers on consistency. Critics argue MSCI applies its proposed financial ratios unevenly across asset classes.
Consider the treatment of real estate investment trusts (REITs) and mortgage REITs (mREITs). MSCI benchmarks routinely feature entities whose balance sheets concentrate heavily on a single asset class—commercial real estate, residential mortgages, or physical property portfolios—and whose revenues and valuations rely entirely on market cycles, rental yields, and continuous capital raises via debt and equity. These entities depend heavily on external capital to scale portfolios, echoing the capital-raising mechanics used by Bitcoin treasury companies.
Yet under MSCI’s proposed framework, real estate asset concentration and capital dependence are deemed compatible with index inclusion, while identical structural strategies involving digital assets are classified as disqualifying non-operating traits. This disparity exposes vulnerabilities in MSCI’s criteria, which rely on subjective definitions of “operations” tailored to exclude disfavored asset classes while protecting traditional ones.
The Structural Crisis of Private Governance
The confrontation between MSCI and Bitcoin treasury companies extends past the crypto ecosystem, illustrating a broader institutional crisis regarding the unaccountable power of private index providers.
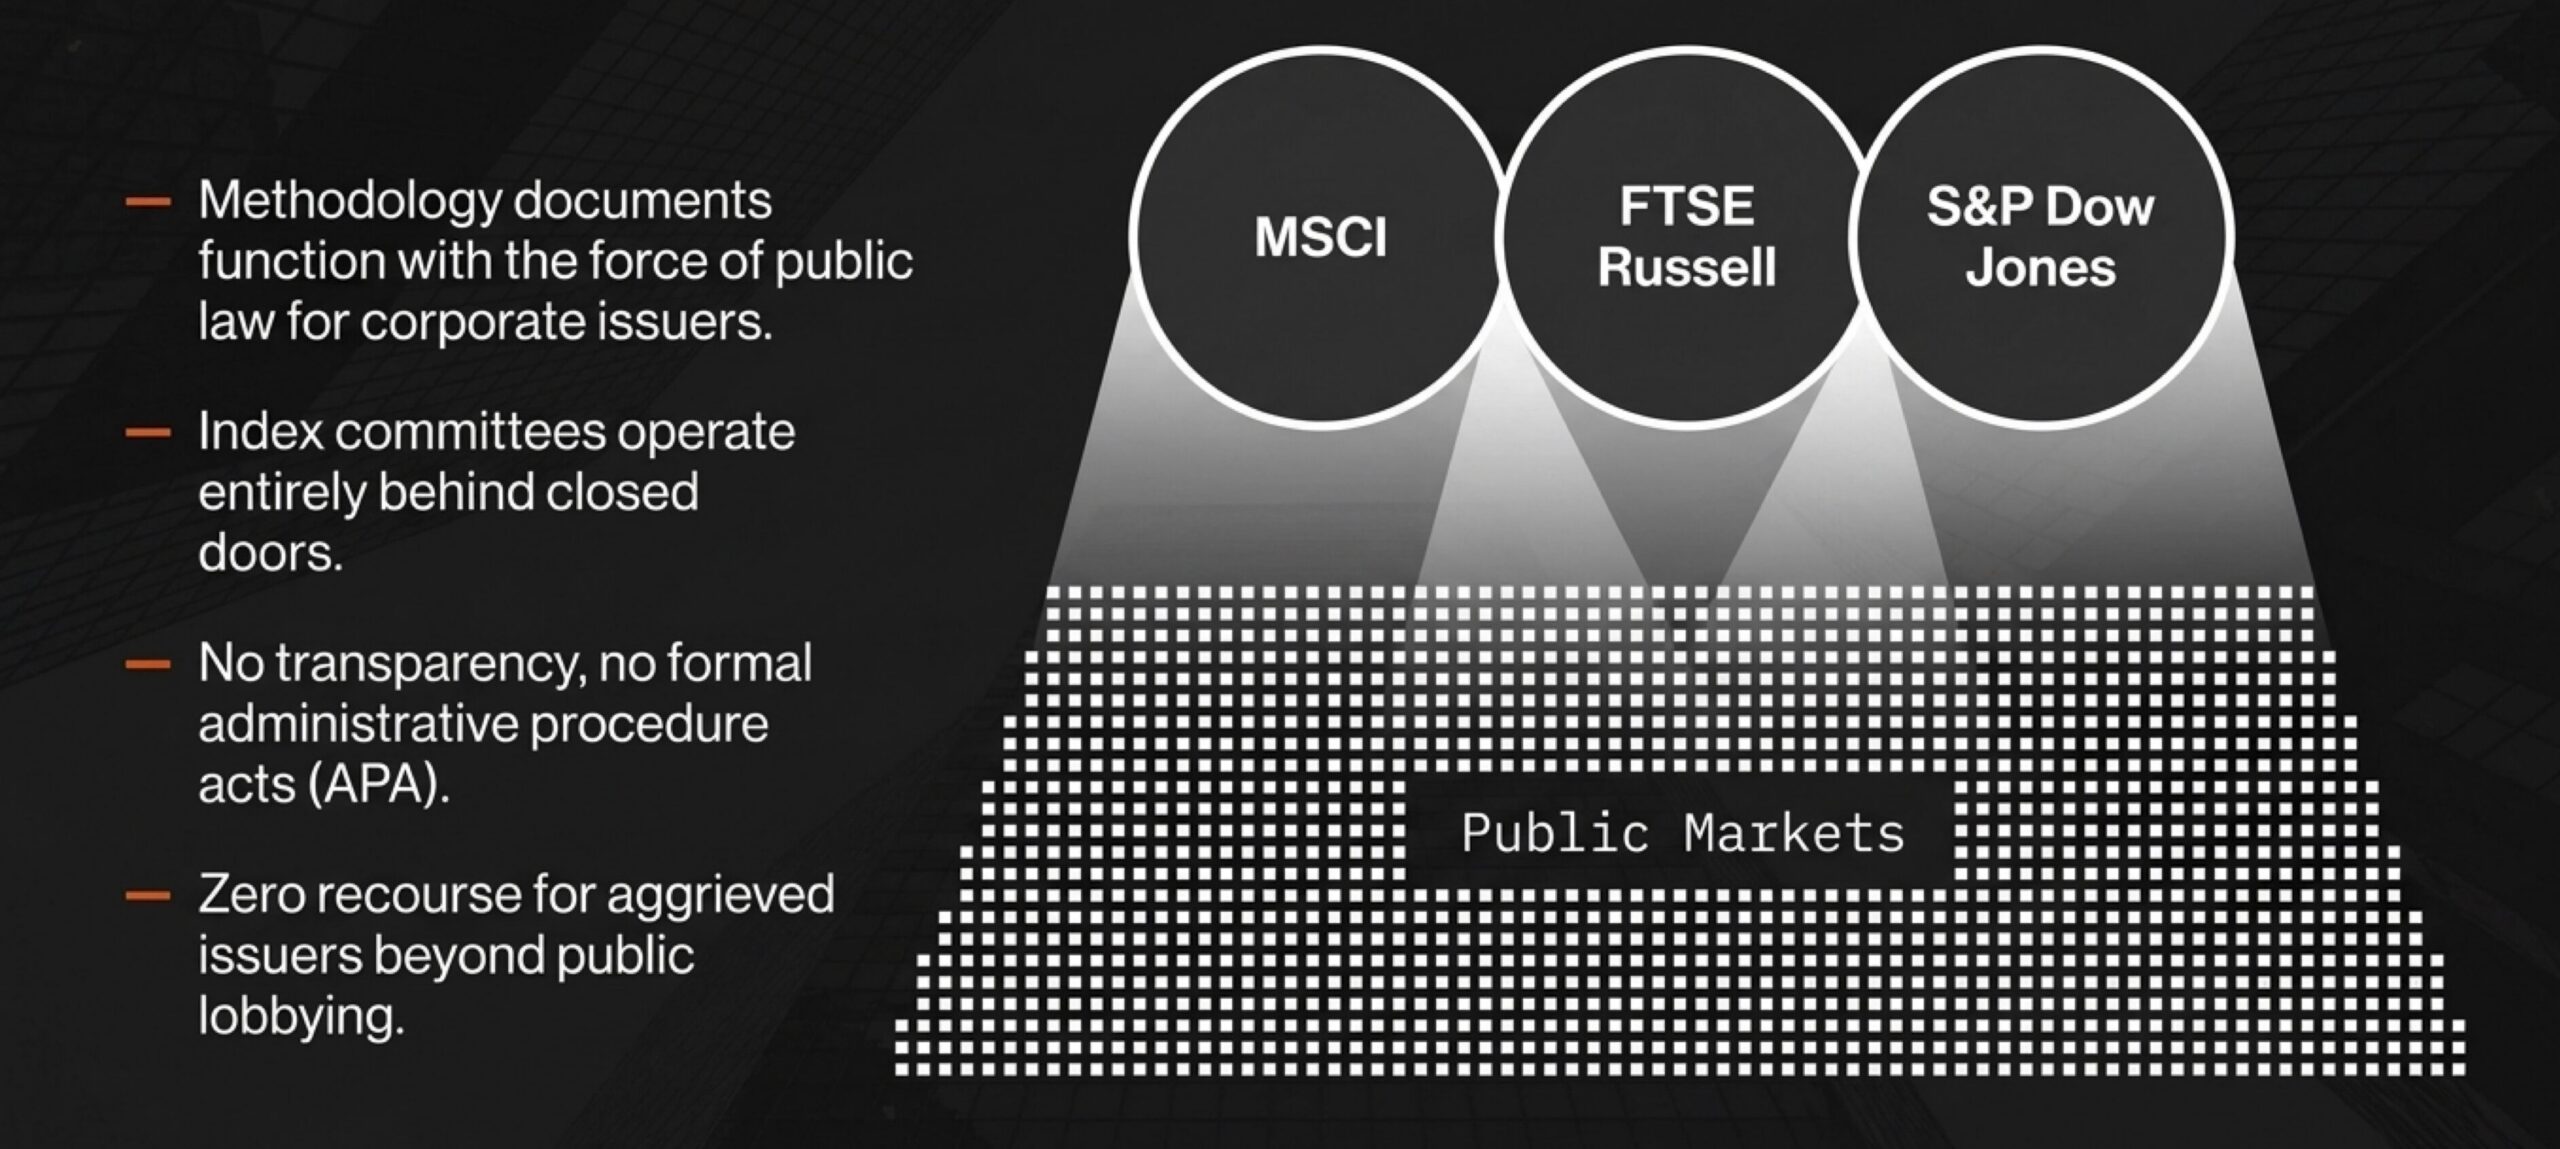
Over the past two decades, capital migration from active management to passive index-tracking funds has concentrated immense economic leverage within an oligopoly of index administrators dominated by MSCI, FTSE Russell, and S&P Dow Jones. These private, for-profit entities produce methodology documents that function with the force of public law for corporate issuers.
When an index provider unilaterally alters inclusion rules to penalize specific corporate treasury models, it engages in private market governance. Unlike regulated public exchanges or statutory securities regulators, index committees operate behind closed doors with limited transparency, no formal administrative procedure acts, and virtually no recourse for aggrieved issuers outside of public lobbying.
If MSCI succeeds in establishing the precedent that holding non-traditional reserve assets on a corporate balance sheet strips a public company of its operating status, it creates a dangerous chilling effect. Today the target is Bitcoin; tomorrow, it could be corporate holdings of physical commodities, strategic technology stakes, gold, real estate, data centers, or alternative monetary reserves conflicting with institutional ESG or benchmark committee preferences. Corporate directors risk losing the sovereign right to optimize balance sheets for shareholder value if it risks excommunication from the passive capital ecosystem.
The Timeline, the Stakes, and the Regulatory Reckoning
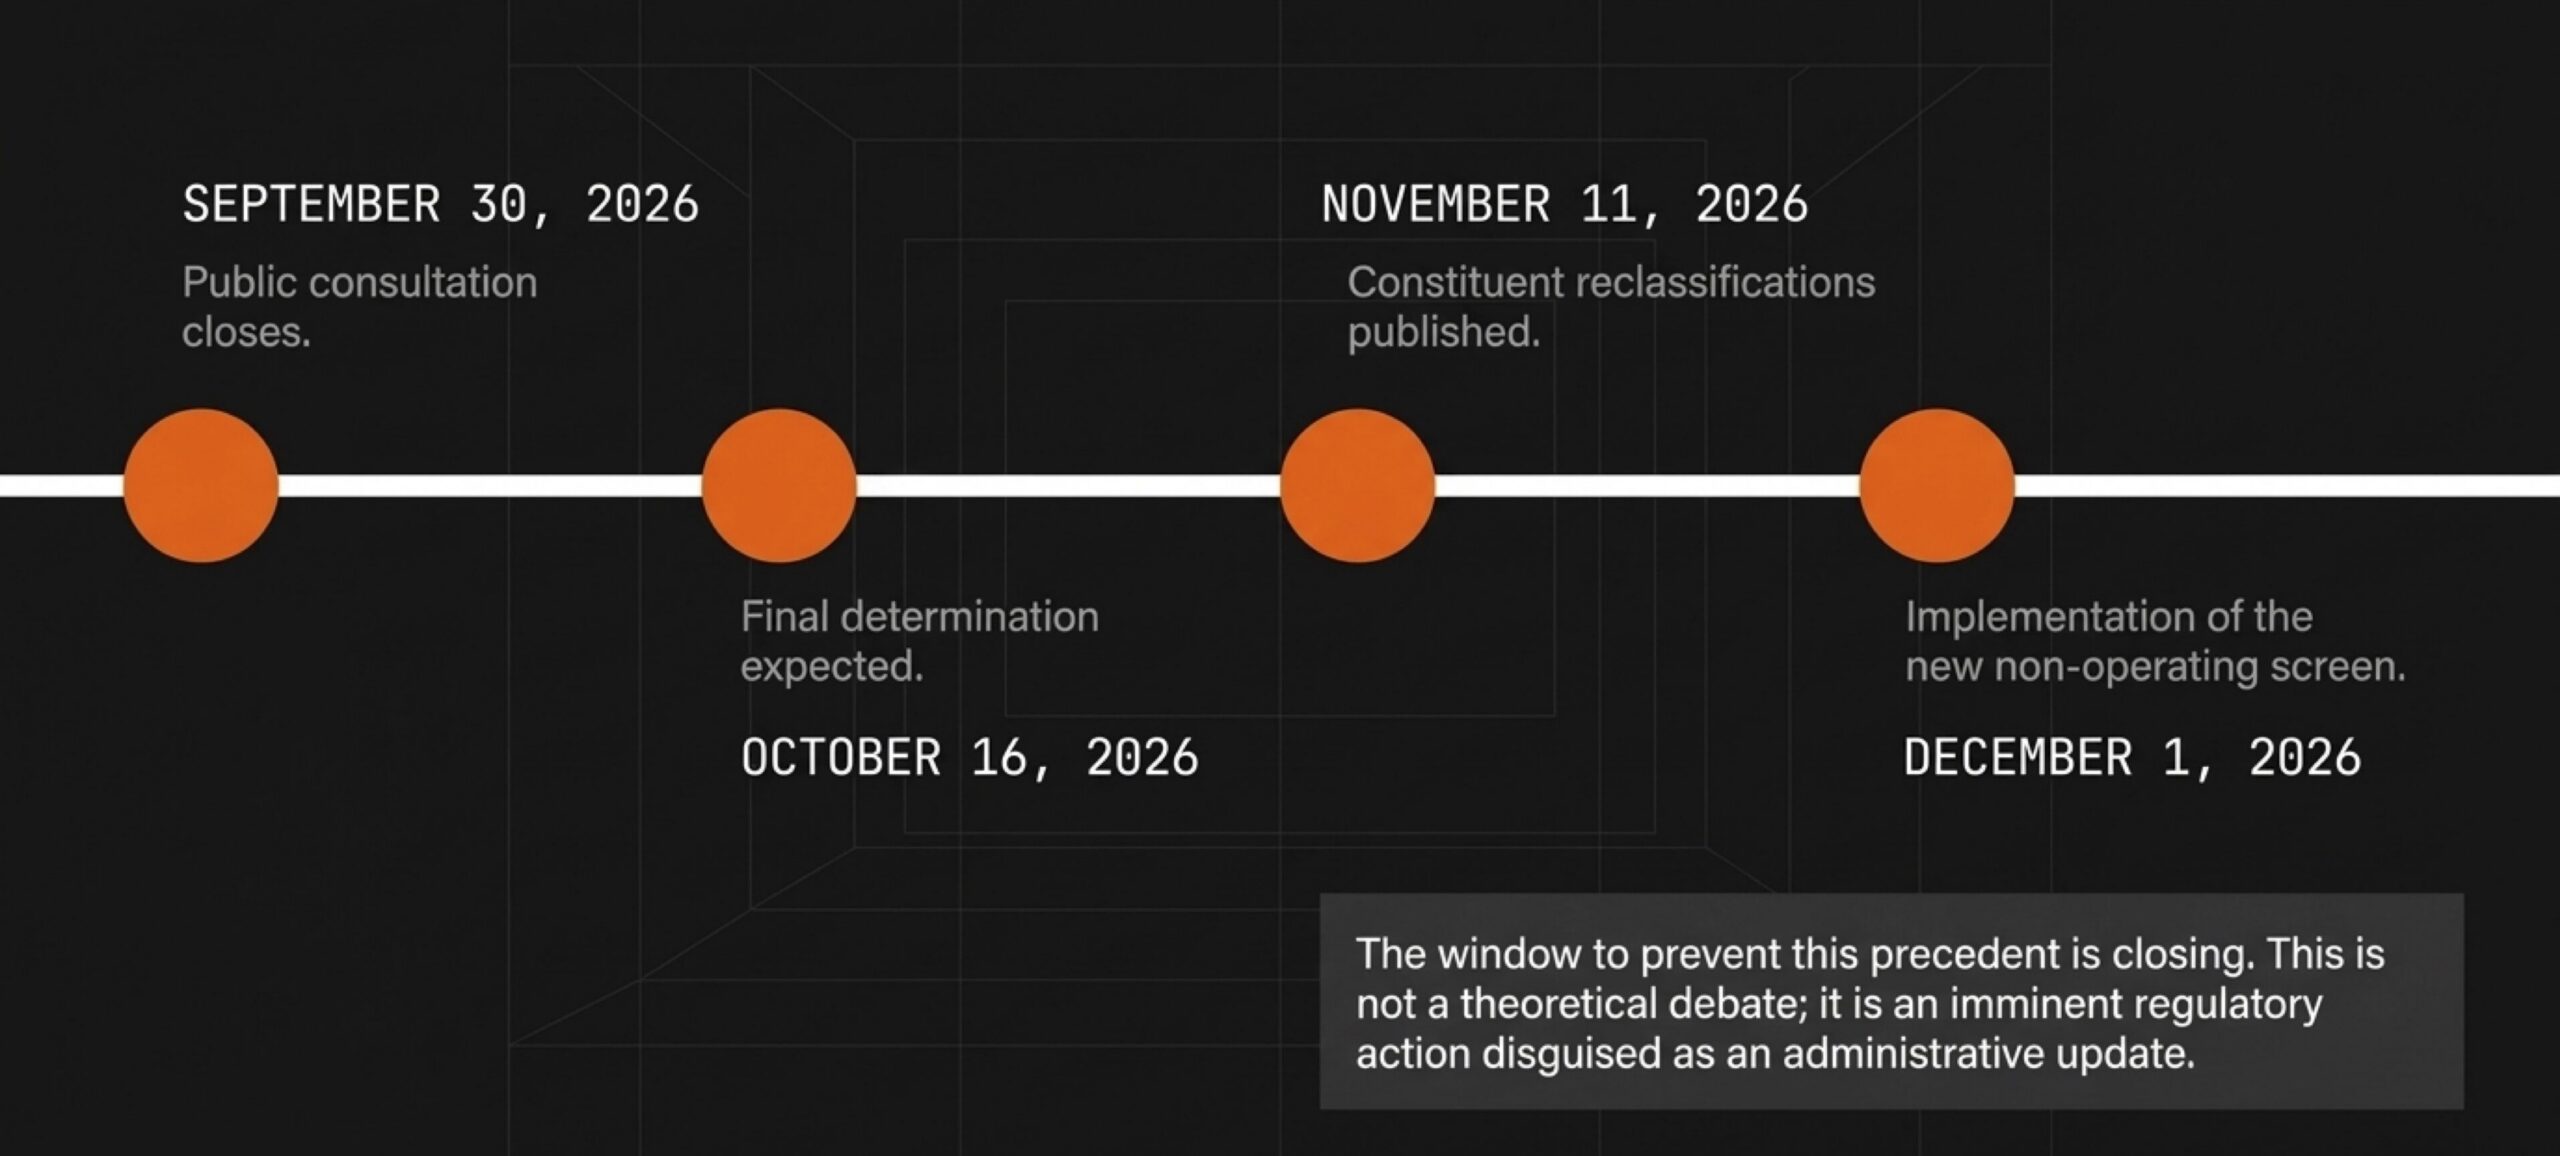
The immediate resolution of this conflict approaches quickly. The public consultation period for MSCI’s non-operating company proposal closes on September 30, 2026, with a final determination expected by October 16, 2026. If adopted in its current form, constituent reclassifications will be published on November 11, 2026, and implemented on December 1, 2026.
For institutional investors, asset managers, and corporate executives, the stakes extend well beyond ticker symbol MSTR. The outcome tests whether public companies retain autonomy to innovate balance sheets in an era dominated by passive gatekeepers, or whether benchmark administrators have crossed the line from measuring markets to regulating them.
The solution requires statutory accountability rather than government micromanagement of index design. The U.S. Securities and Exchange Commission and global securities regulators must stop treating index providers as invisible software plumbing. When an index committee’s discretionary classifications dictate corporate access to capital, distort price discovery, and bypass standard administrative notice-and-comment safeguards, that committee acts as a de facto market regulator.
Regulators must revisit the framework governing dominant index providers under the Investment Advisers Act, demanding transparent due process, strict standards against arbitrary discrimination, and formal accountability for decisions altering capital formation.
Until market authorities recognize that index providers have become systemic gatekeepers, the free market for corporate control will no longer be governed by shareholders, boards, and public statutes—it will remain at the mercy of unelected private arbiters in New York and London.
Take Action to Protect Index Neutrality
The boundary between measuring market value and regulating corporate behavior is being erased. MSCI’s proposed “non-operating company” screen threatens to penalize balance-sheet innovation, misclassify legitimate operating businesses, and set a dangerous precedent for private governance in capital markets.
Don’t let private index administrators dictate corporate treasury strategy behind closed doors. The public consultation window closes on September 30, 2026.
Join business leaders, institutional investors, and advocates for open capital markets:
- Sign the Open Letter: Add your voice or your organization’s signature to demand that MSCI withdraw the proposed screen and publish all market feedback at msci.bitcoinforcorporations.com.
What is the core conflict between MSCI and corporate Bitcoin holders?
MSCI is proposing a new framework to screen out “non-operating companies” from its global indexes, which threatens to remove major public Bitcoin treasury firms like Strategy from major benchmarks like the GIMI.
When does MSCI’s consultation on non-operating companies close?
The public consultation period for the proposal closes on September 30, 2026, with a final determination expected by October 16, 2026.
How does MSCI define a non-operating company under the proposed screen?
MSCI applies a primary balance-sheet test (failing a 50 percent operating asset threshold) followed by an exclusion screen measuring five specific financial ratios, resulting in classification as a non-operating entity if at least four metrics fail.
What are the primary criticisms against MSCI’s proposed methodology?
Critics argue the rules rely on subjective definitions of business operations, apply asset-concentration standards inconsistently compared to real estate trusts, and expand the unchecked regulatory power of private index providers.